What Not to Keep in Your Car
Keep valuables, personal documents, and anything flammable or heat-sensitive out of your car, because your policy may not cover what's lost.
Your policy covers the car, not everything inside it
Auto insurance is built to pay for the vehicle and, depending on your coverage, for theft of the vehicle itself. Personal belongings inside the car are usually a different story. If someone smashes a window and takes a bag, laptop, or gift you left on the seat, your auto policy often won't pay for those items at all. That gap surprises a lot of people only after it happens.
In many cases, stolen personal property is actually covered under a renters or homeowners policy, not your car insurance, because the item belongs to you as a person rather than to the vehicle. But that depends entirely on what kind of policy you carry and what it excludes, so you need to check your own policy or ask your insurer directly rather than assume either way.
Beyond theft, there's damage from heat, cold, and just being inside a car all day. Electronics, medications, and anything in a spray can or aerosol container can warp, leak, or become dangerous when temperatures swing. That's not an insurance problem so much as a practical one, but it often ends up costing you the same way a theft would.
Then there's the information risk. Registration, insurance cards, and anything with your home address or account numbers can be used against you if your car is broken into or stolen outright. This isn't about what your policy pays, it's about what someone could do with what they find. The safest habit is treating your car like a space you pass through, not a place you store things.
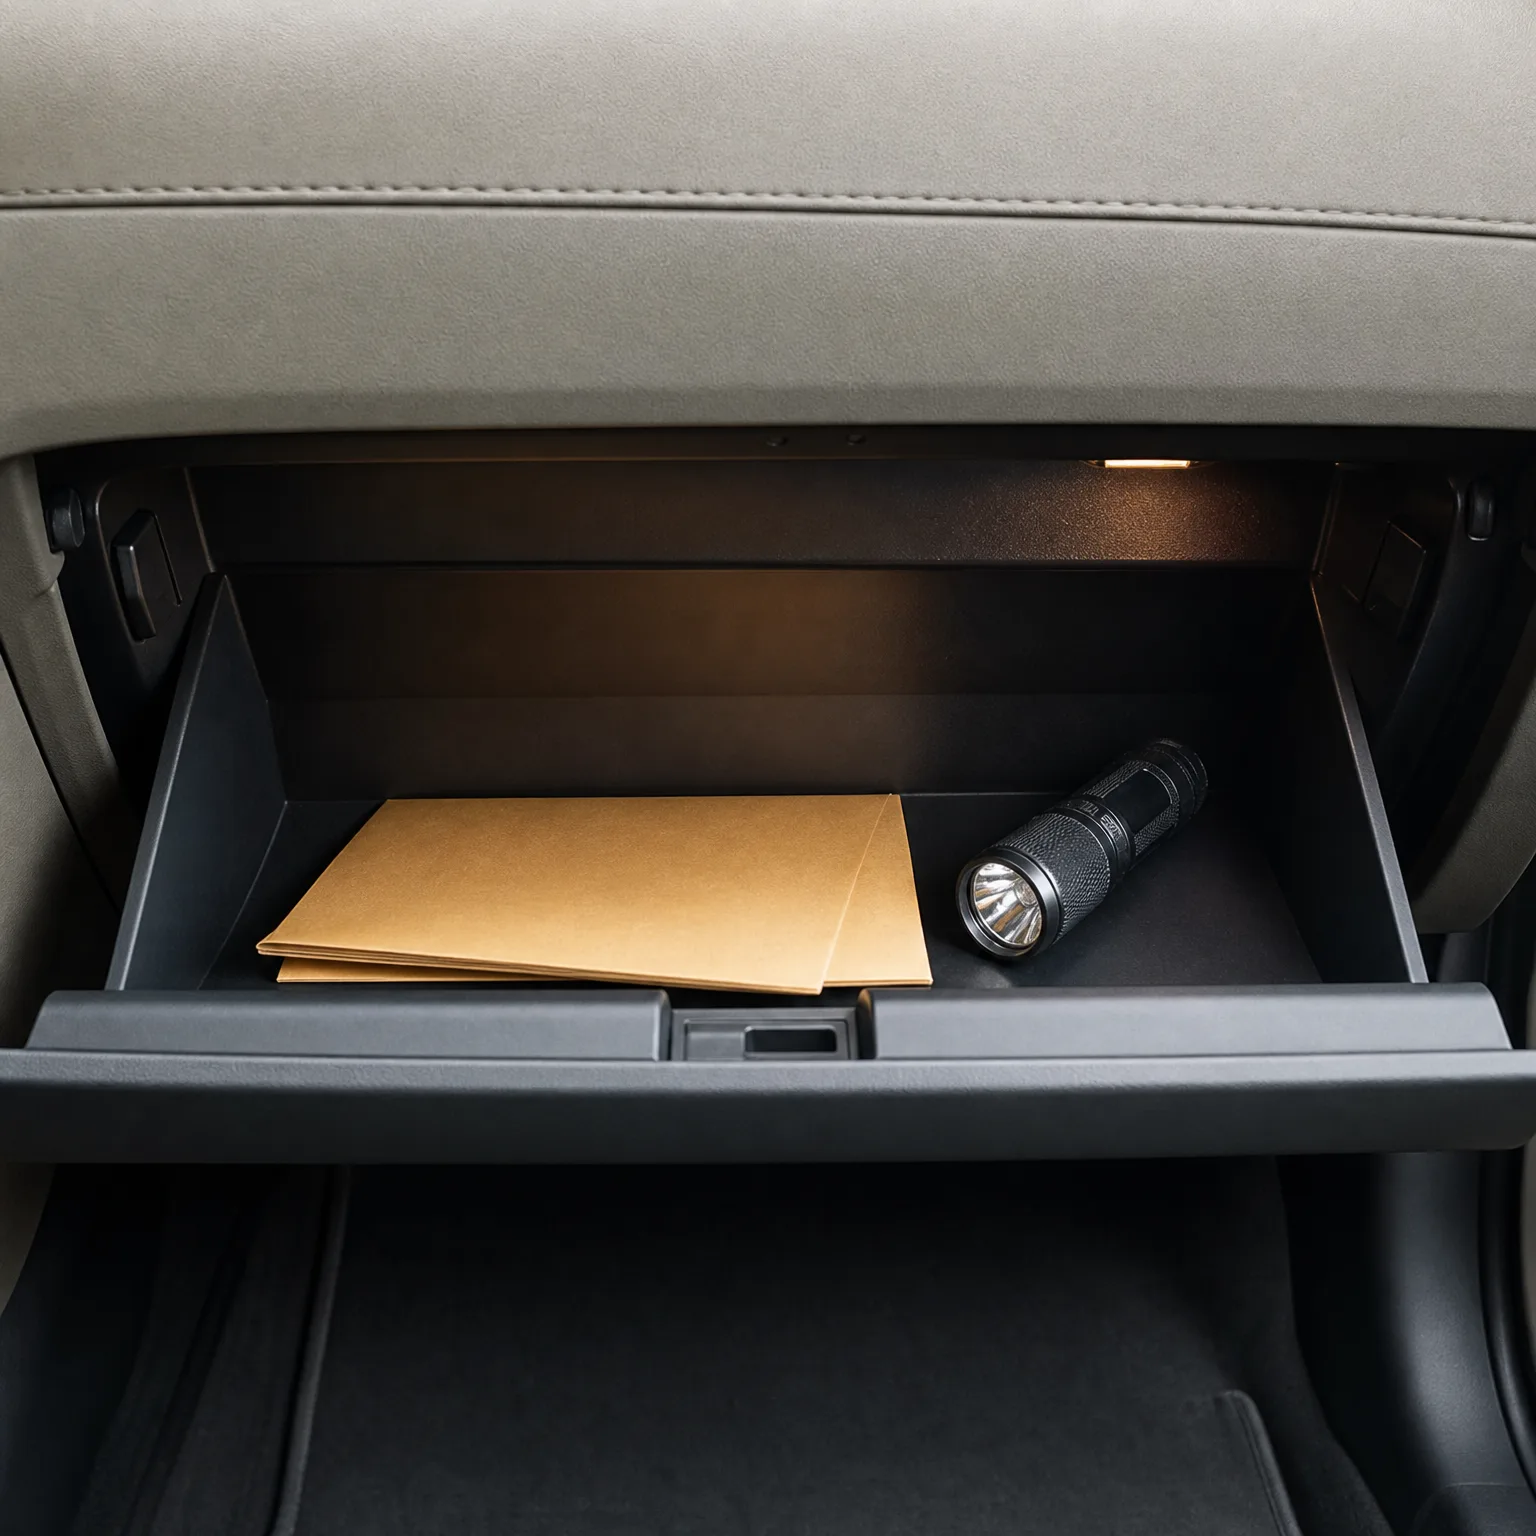
What to take out of your car and why
- Spare keys or remotes These hand a thief your home address and a way in. Keep one spare at home or with a trusted person instead.
- Personal documents Mail, bills, or anything listing your address or account numbers helps someone steal your identity. Carry only what you need that day.
- Valuables and electronics Laptops, bags, and gadgets left visible invite break-ins and often aren't covered by your auto policy. Bring them inside or lock them out of sight.
- Medications, heat items Temperature swings can ruin or spoil items left in a hot or cold car. Store these at home and bring only what you need for the trip.
- Aerosols and flammables Spray cans and lighters can become dangerous in extreme heat. Keep them out of the car entirely rather than risk it.
Once you know what your policy covers inside the car, compare quotes to see what protection you're really getting.
Clearing out your car versus leaving things in it
If you do
You lower the odds of a break-in since there's nothing visible worth taking. If something does happen, you're not out a laptop, medication, or personal documents, and you've removed the easiest way for a thief to find your home address or identity.
If you don't
A visible bag or gadget can be the reason someone targets your car specifically. If it's stolen, you may find your auto policy won't reimburse you at all, and you're left filing a claim on a different policy, or paying out of pocket with nothing to show for it.
Does homeowners or renters insurance cover stuff stolen from my car?
Often yes, but not always, and it depends entirely on your specific policy. Many renters and homeowners policies cover personal property anywhere you own it, including inside a parked car, because the coverage follows the item rather than the location. That means a stolen laptop or bag might be reimbursed under that policy even though the theft happened in your vehicle.
But this isn't universal. Some policies limit coverage for property stolen from a vehicle, or apply a separate deductible, or exclude certain categories of items. The only way to know for sure is to read your policy's personal property section or call your insurer and ask specifically about theft from a car. If you don't have renters or homeowners coverage at all, you may have no protection for stolen belongings, which is its own reason to look into one.
Your car insurance protects the vehicle, not what's inside it, so treat your car like a hallway, not a closet.